China orders every province and central state firm to put humanoids to work in real sites, targeting 100 use cases and 10,000-unit deployment capacity by end-2026
China's industry ministry and its state-asset regulator have launched a 2026 special action that requires each provincial region to open at least 20 real-world training scenes and each central state-owned enterprise at least 10. The notice, dated June 3 and published June 8, sets a year-end goal of more than 100 high-value application scenarios and the ability to deploy humanoid and embodied AI robots at a scale of tens of thousands of units.
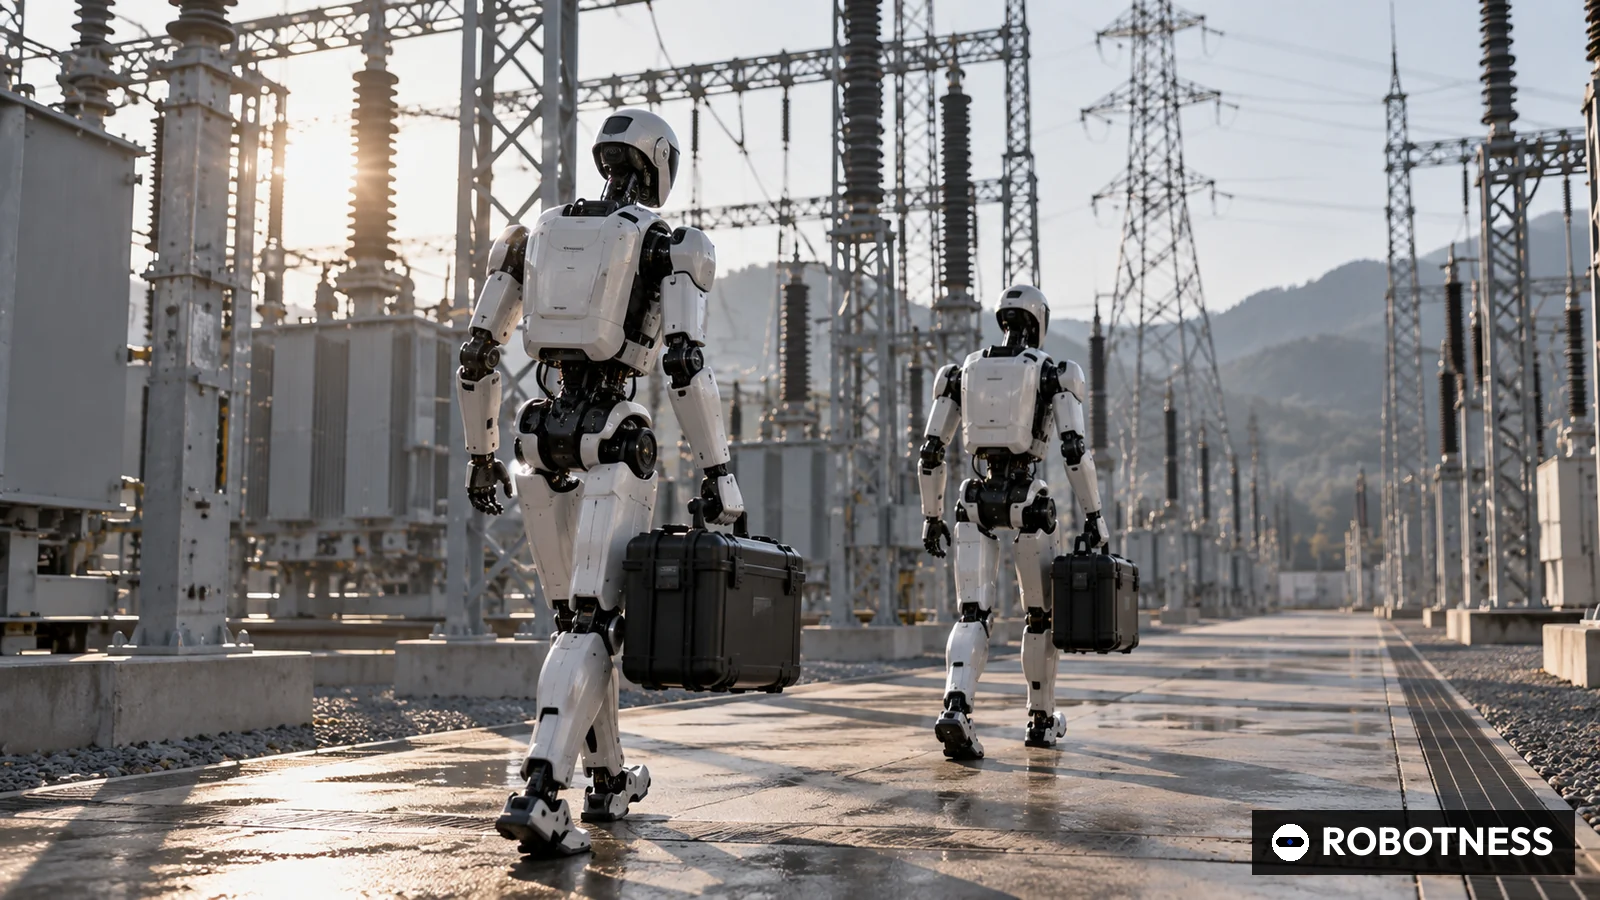
China's Ministry of Industry and Information Technology (MIIT) and the State-owned Assets Supervision and Administration Commission of the State Council (SASAC) have ordered provincial governments and central state-owned enterprises to move humanoid robots out of showrooms and into working factories, warehouses, hospitals and emergency sites, according to a joint notice the MIIT published on June 8, 2026.
The document, numbered Gongxin Ting Lian Ke Han [2026] No. 256 and dated June 3, launches what the two agencies call a 2026 special action on real-scene training for humanoid robots and embodied intelligence. Its stated aim is to make the routine deployment of such robots in real production and living environments normal practice and to speed up scaling. By the end of 2026 the agencies want validation and regular deployment completed in representative scenarios, more than 100 high-value application scenarios distilled, and what the notice describes as deployment capability at the ten-thousand-unit level.
The quotas are specific. Each provincial-level region must select no fewer than 20 key scenario units, and each central SOE must select no fewer than 10 scenarios tied to its own industry. The fields listed in the notice cover manufacturing, inspection and analysis, repair and maintenance, warehousing and logistics, catering and retail, medical and elderly care, workplace safety, emergency rescue and disaster prevention. Provinces may later recommend up to 10 outstanding training programmes and central SOEs up to five.
The agencies set two deadlines. Work plans were due to the MIIT and SASAC by June 30, 2026, and summaries with performance statistics are due by November 30, 2026. That compresses the whole cycle of site selection, robot procurement, task training and validation into roughly five months.
The notice organises the work around six tasks. Beyond building the training spaces, it asks user organisations and robot makers or application service providers to lead an innovation consortium for each scenario, bringing in model developers, component suppliers and research institutes. It calls for high-quality, high-fidelity datasets, for computing setups that mix cloud, edge and on-device processing including off-grid autonomy, and for safety functions it names as collision detection, force limiting, emergency braking and a black-box recorder.
The remaining tasks deal with proof and money. Agencies want test procedures and pass criteria for application validation, and they explicitly endorse exploring a humanoid-robot-as-a-service model. The notice tells local authorities to coordinate equity, debt and insurance tools to provide full-chain financial services, to push participants into standardisation committees, and to train staff who understand both the core technology and the target industry.
The pairing of the MIIT with SASAC is the notable design choice. SASAC supervises the central SOEs that run China's grids, ports, steel mills, oil fields, railways and telecom networks. By giving each of them a scenario quota, Beijing turns its largest industrial buyers into first customers for domestic humanoid makers at a time when commercial demand outside research and exhibition use is still thin.
The target sits against modest disclosed volumes. UBTech Robotics reported in its 2025 annual results, filed with the Hong Kong exchange on March 31, 2026, that it sold 1,079 full-size humanoid robots in 2025 and had capacity for more than 6,000 units at year-end. AgiBot said at its partner conference on April 17 that its ten-thousandth robot had rolled off the line this year. Unitree's listing documents show 2025 revenue of RMB1.70 billion. A national capability to deploy tens of thousands of units in working sites would therefore require the output of several leading makers combined.
The open questions are about measurement and quality. The notice speaks of capability at the ten-thousand-unit level rather than a count of robots actually installed, and it does not define what qualifies as regular deployment. Nor does it set a budget; financial support is described as coordination of equity, debt and insurance instruments rather than as a central fund. The November 30 reporting date is the first point at which the agencies will gather comparable statistics.
- Notice target: deployment capability
- 10,000
- units (ten-thousand-unit level)
- by end-2026
- MIIT and SASAC
- Notice target: high-value scenarios
- 100
- scenarios (more than)
- by end-2026
- MIIT and SASAC
- UBTech full-size humanoids sold
- 1,079
- units
- FY2025
- UBTech annual results
- UBTech full-size humanoid capacity
- 6,000
- units (more than)
- end-2025
- UBTech annual results
- AgiBot robots rolled off line
- 10,000
- units (cumulative)
- as of 2026
- AgiBot APC 2026
- Unitree revenue
- 1,699.27
- RMB million
- FY2025
- Unitree listing announcement
Figures as disclosed by issuers; no estimates. UBTech capacity and AgiBot output are stated as thresholds (more than / ten-thousandth unit). Unitree revenue converted from RMB169,926.93 ten-thousand.
As of Oct 1, 2026
ROBOTNESS analysis
The notice converts China's humanoid push from a supply-side subsidy story into a procurement mandate, and the central SOEs are the lever that matters.
The evidence is in the quotas. Thirty-one provincial-level regions at 20 scenes each imply at least 620 provincial scene units before counting the central SOEs, each of which must add 10. That creates a guaranteed field of pilot sites for vendors whose sales so far have leaned on universities, exhibitions and government showcases.
The strongest counter-argument is that mandated pilots can generate activity without productivity. A five-month window and a reporting target framed in scenario counts invite deployments sized for the November statistics rather than for return on investment, and the notice offers no cost benchmark against human labour.
Bull case: SOE sites produce the task data the notice asks for, safety and test rules become standards, and the robot-as-a-service model spreads cost. Domestic makers then reach volume in 2027 on the back of real orders, and component suppliers gain scale that lowers unit prices.
Bear case: scenes are chosen for visibility, robots spend most of their time under teleoperation or supervision, and procurement fades once the reporting cycle ends. Vendors expand capacity against demand that proves to be policy-timed.
Signals to watch:
- November 30, 2026: provincial and SOE summaries and the first national tally of deployed scenarios.
- Any MIIT list of the outstanding training programmes recommended by provinces and SOEs after November.
- First published validation test procedures or standards drafts referenced in the notice, expected around the end of 2026.
- MIIT General Office and SASAC General Office
- Work plans by June 30, 2026; summaries by November 30, 2026
- 100+ high-value scenarios; deployment capability at ten-thousand-unit level
- At least 20 key scenario units per provincial-level region
- Gongxin Ting Lian Ke Han [2026] No. 256
- At least 10 scenarios per central SOE
- June 3, 2026 / June 8, 2026
- Collision detection, force limiting, emergency braking, black box
Why it matters
Chinese humanoid policy until now has largely supported supply: industrial parks, subsidies, competitions and model funding. This notice is the first national instrument we have seen that assigns demand-side quotas by name to both provincial governments and SASAC-supervised central enterprises, and it comes with fixed reporting dates.
For vendors, the practical effect is a pipeline of pilot sites with institutional buyers. Central SOEs operate assets where labour is dangerous, remote or ageing, which aligns with the notice's emphasis on safety production, inspection and emergency rescue. These are environments where a robot that works 60 percent of the time can still be justified if it removes people from risk.
Rival analysis
The beneficiaries are those vendors that can supply a full stack quickly: hardware, task models, data collection and service. UBTech has disclosed the largest industrial humanoid volumes among listed players, with 1,079 full-size units sold in 2025. AgiBot claims cumulative output of 10,000 robots and has already built a leasing platform it calls Qingtian Rent, which matches the notice's robot-as-a-service language. Unitree's strength is price and volume in research and education platforms rather than industrial task integration.
The consortium design favours incumbents with SOE relationships and system integrators that can stitch models, grippers and safety controls into a site. Smaller startups are likely to enter as component or model partners inside a consortium led by a user organisation or a larger robot maker.
Valuation context
The notice contains no direct fiscal outlay, so it does not change revenue models overnight. Its value to listed and soon-to-list companies lies in visibility: scenario wins in SOE settings will feature in disclosures and roadshows. Unitree's STAR prospectus and UBTech's Hong Kong filings already tie their growth narratives to industrial deployment, and this mandate gives that narrative a policy anchor.
Investors should separate scenario counts from revenue. A scenario can be one robot. Until the November statistics show units and hours, valuation gains linked to this notice rest on expectation.
Supply-chain implications
The required safety functions, force limiting and collision detection in particular, push demand toward joint torque sensing, current-based force estimation and certified emergency stop circuitry. The call for off-grid autonomy and cloud-edge-device computing favours domestic edge processors and battery packs designed for long shifts.
For reducers, frameless motors, screws and dexterous hands, the mandate adds orders but also standardisation pressure. Consortia sharing data and test procedures across sites are more likely to prefer interchangeable modules.
Signals to watch
First, provincial work plans submitted by June 30 may surface through local government websites in July and August, naming sites and vendors. Second, the November 30 summaries are the first data point on actual deployments. Third, any follow-on notice from the MIIT selecting outstanding programmes would indicate which vendors the centre is backing.
Also watch SASAC-supervised groups in power, petrochemicals and shipbuilding announcing humanoid procurement frameworks, and whether insurers launch products tied to the notice's call for insurance tools.
Analyst view
Thesis: the notice will accelerate real-site deployment in China in the second half of 2026, but the first reported figures will overstate productive use.
Confidence: medium. The quotas and dates are concrete and SOEs reliably comply with SASAC directives, which supports the acceleration call. The weakness is that the document measures scenarios and capability rather than robots in productive service, and gives no funding figure, so the economic depth of deployment is uncertain.
Questions you should be asking
How will the MIIT define regular deployment, and will it publish unit counts or only scenario counts?
Will central SOEs buy robots outright, lease them through service models, or host vendor-funded pilots?
Which standards committee will own the validation test procedures, and will they become national standards?
How much teleoperation will be permitted in a scenario reported as deployed?